


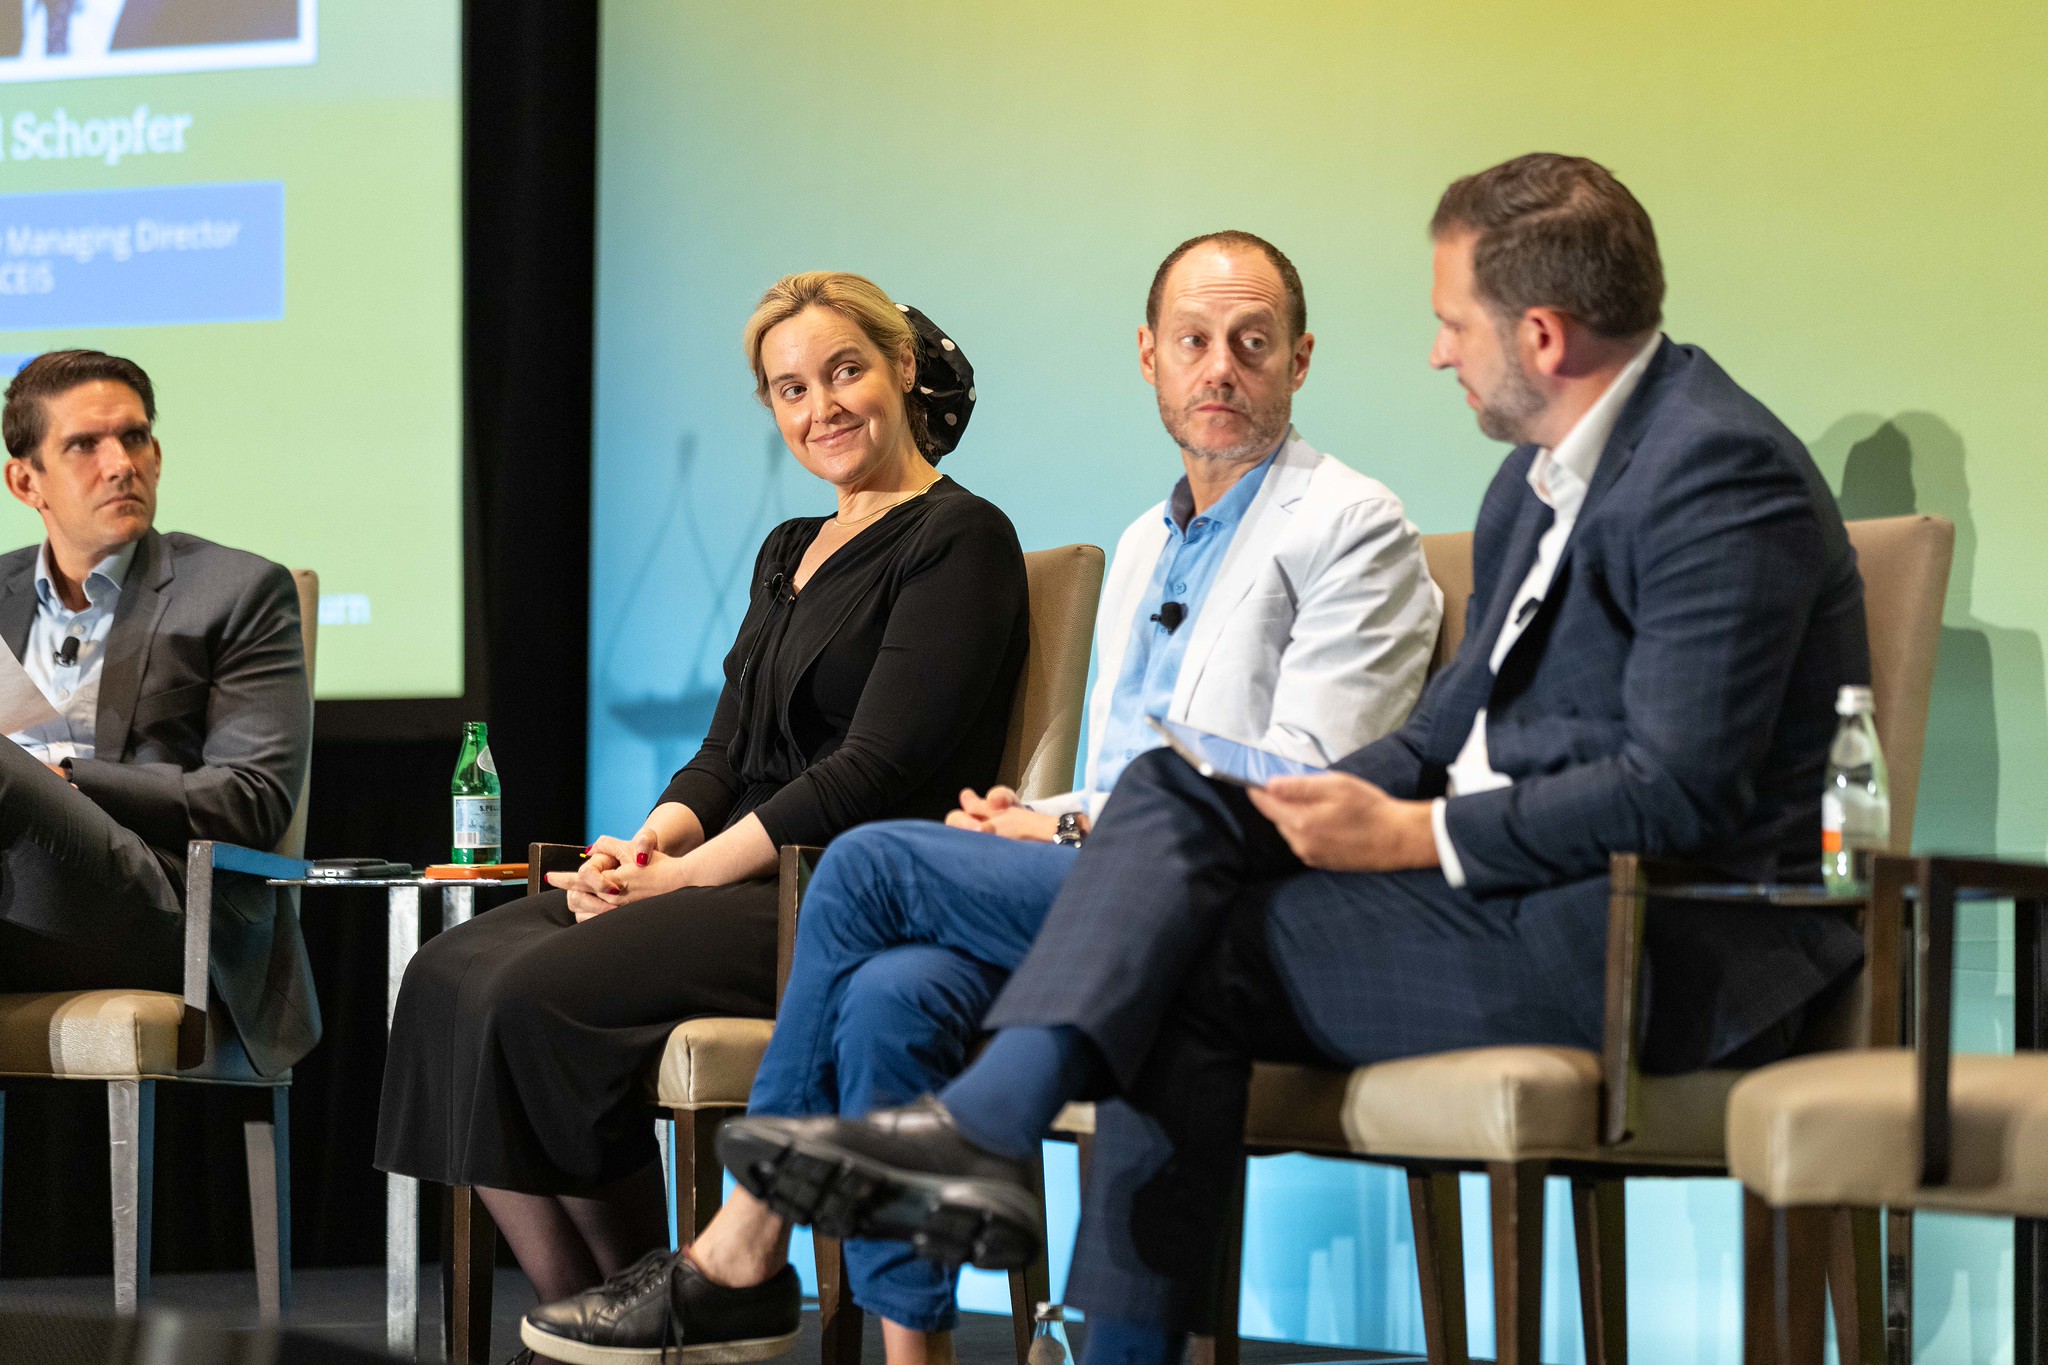
A SuperReturn panel gets specific about where evergreen fund structures work, where they don’t, and what happens under redemption stress.
For forty years, private markets ran on one access point: a closed-end drawdown fund, a ten-year term that usually ran twelve, and a manager whose only real job was finding good deals and calling capital when they were ready. That model is now splitting in two, and a panel at SuperReturn US West spent thirty minutes making the case for why — and quietly admitting where the new model’s edges haven’t been stress-tested.
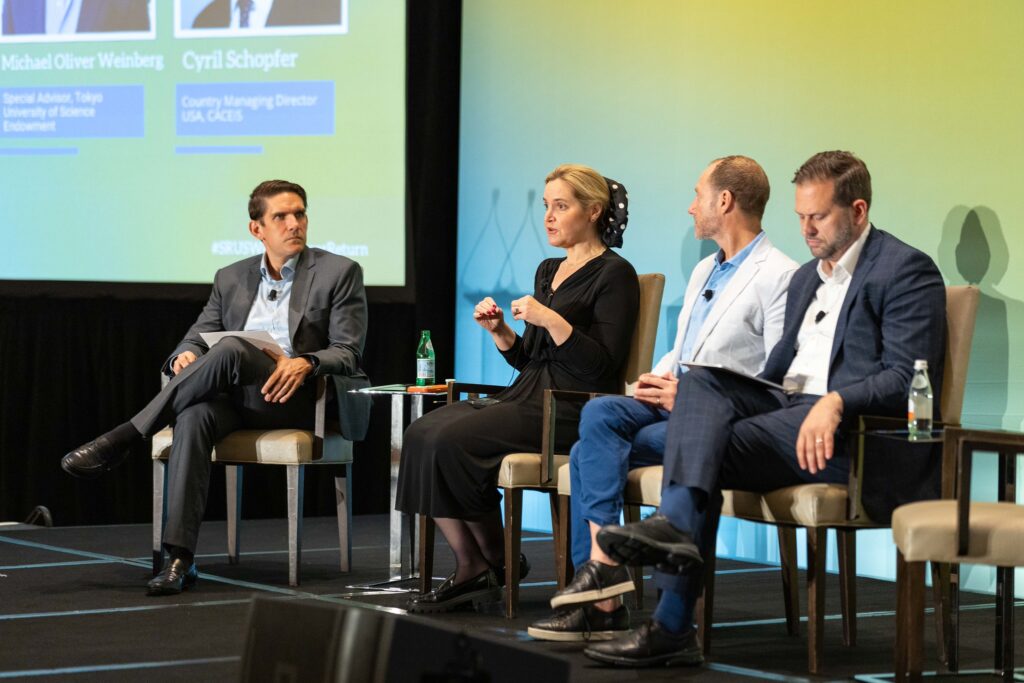
The panel, moderated by Joshua Clarkson of Prosek Partners, brought together Monique Austin (HarbourVest Partners, Head of Evergreen Solutions), Michael Oliver Weinberg (Tokyo University of Science Endowment, also teaching at Columbia Business School), and Cyril Schopfer (CACEIS, Country Managing Director USA).
Between them: a manager building evergreen products, an allocator who’s run both evergreen and drawdown vintage funds at scale, and a fund administrator who handles the operational plumbing for both.
Why the Model Split
Austin laid out the mechanical story. Drawdown funds worked fine for managers; commit capital, call it when needed, return it on realization, but put real weight on investors, who had to manage cash across five-plus fund commitments a year, each generating roughly eighty capital calls and distributions over its life. That was manageable for large institutions with dedicated teams. It wasn’t for smaller allocators or wealth platforms.
The real break came about five years ago.
Post-2021, distribution yields on private portfolios roughly halved, from the 20-25% range down to 12-15%. Institutional investors who depended on those distributions to fund new commitments suddenly couldn’t re-up at the pace managers expected.
At the same time, wealth distributors — tired of administering drawdown mechanics for retail-adjacent clients — told managers plainly that access to that capital now required an evergreen structure: one subscription, one redemption, instead of dozens of calls and distributions.
Where the Model Actually Struggles
The panel was specific, not just promotional, about which asset classes fit an evergreen wrapper and which don’t.
Private credit fits most naturally: there’s a maturity date, cash interest, something resembling a liquidity schedule.
Real estate is the next step down.
Private equity and venture are harder, and venture specifically drew skepticism: Austin argued that a portfolio of traditional blind-pool venture assets is “definitely” not easy to run in evergreen format, given long hold periods and volatile marks.
The workaround managers have converged on is secondaries — buying into already-priced positions closer to a realization event, often at a discount, which shortens duration and reduces the blind-pool risk. Schopfer noted that from CACEIS’s vantage point administering funds across asset classes, there’s no single template; every evergreen structure they service is built differently to solve the same liquidity problem.
The Valuation Tension Nobody Fully Resolved
The sharpest exchange was about NAV. Evergreen funds have to strike net asset value monthly, sometimes daily, on portfolios of private companies that are, by nature, priced infrequently and in arrears. That NAV sets the price at which investors buy and sell and the base on which the manager collects fees — a structural conflict of interest that Austin acknowledged directly, framing the fix as process: an independent valuation agent, a valuation committee separate from the investment team, and back-testing to measure how far interim marks drifted from later, harder marks.
Weinberg pushed further, drawing on his experience allocating at First Republic and APG (the Dutch pension fund). In a vintage drawdown fund, he noted, every investor is “in the same boat” — everyone commits and exits on the same terms, and the final NAV is trued up and irrefutable. In an evergreen fund, investors enter and exit continuously at different NAVs, and some pay incentive fees along the way — a practice the SEC has permitted but that Weinberg said he isn’t fully convinced is appropriate, since it opens the door, intentionally or not, to favoring some cohorts of investors over others.
The Liquidity Everyone Agreed Is Not Real
The clearest moment of consensus came in the lightning round, when panelists were asked to name the biggest misconception about evergreen funds. The answer, stated plainly: evergreen funds are not liquid.
A standard 5% quarterly redemption gate means 95% of the fund remains illiquid at any given time. What evergreen structures actually provide is a higher degree of control over the timing of illiquidity — the ability to request redemption at NAV in normal markets, rather than sell at a discount on a secondary market, which was the only liquidity option in the first wave of publicly listed permanent-capital vehicles twenty years ago.
Weinberg added a second, more candid answer: for private wealth clients and smaller institutions in particular, the real advantage of evergreen products may simply be operational — investing once instead of managing cash lines against a string of vintage-fund commitments — rather than a demonstrated improvement in net returns.
What’s Still Unresolved
Schopfer’s closing point was the one worth remembering: the actual test of an evergreen fund isn’t how it performs when subscriptions are strong. It’s what happens when redemption requests exceed the fund’s available liquidity — a scenario the panel referenced only in the abstract, pointing to prior gating episodes in non-traded REITs and, more recently, in large evergreen credit vehicles, without naming specific funds or events by name. That scenario, more than any of the structural fixes discussed, is what will determine whether the current wave of evergreen products holds up at scale.
FAQ
What is the difference between an evergreen fund and a drawdown fund?
A drawdown fund calls investor capital over a multi-year investment period and returns it as assets are realized, typically over a ten-to-twelve-year life. An evergreen fund is open-ended: investors subscribe once, gain immediate exposure to an existing portfolio, and can request redemptions on a periodic basis instead of waiting for the fund to wind down.
Are evergreen funds actually liquid?
Not fully. Most cap redemptions at a set percentage per period, often around 5% per quarter, which means the large majority of the fund stays illiquid at any given time. What the structure actually offers is more control over the timing of that illiquidity, not on-demand access to cash.
Why does an evergreen fund’s NAV create a conflict of interest?
Evergreen funds have to strike net asset value frequently, sometimes monthly, on portfolios of private assets that are priced far less often. That NAV sets the price at which investors buy and sell, and it’s also the base the manager gets paid fees on — which is why independent valuation committees and back-testing exist, as a way to manage that tension rather than remove it.